Before you fall in love with a North Carolina home, find out what it will cost to protect it.
You’ve found the home. The kitchen feels right, the location fits your lifestyle, and the mortgage payment appears manageable. Then the homeowners insurance quote arrives—and your monthly budget looks different.
For buyers in Lake Norman, Cornelius, Davidson, Mooresville, Denver, Huntersville, and surrounding communities, insurance deserves attention early in the homebuying process. The premium, deductible, and coverage terms all influence the financial picture.
Can homeowners insurance affect how much home you can afford? Yes. It adds to your ownership costs, and lenders generally include it when evaluating your housing payment and loan qualification. A property-specific quote helps you make a more informed decision.
Why North Carolina Buyers Should Pay Attention Now
Under a settlement announced by the North Carolina Department of Insurance, average statewide homeowners insurance base rates increased by 7.5% on June 1, 2025, and another 7.5% on June 1, 2026. These are statewide averages for base rates—not a prediction that every homeowner’s premium will rise by the same amount. Changes vary by territory, insurer, property, and coverage.
That distinction matters. A seller’s current insurance bill can provide background, but buyers should obtain their own quotes rather than assume they will pay the same amount.
The North Carolina Department of Insurance encourages consumers to compare policies, understand coverage, and consider how deductible choices affect their costs.
The Monthly Payment You See May Be Missing a Piece
When evaluating affordability, account for principal, interest, property taxes, homeowners insurance, applicable mortgage insurance, and HOA dues. Maintenance and repair reserves deserve their own place in your budget, too.
Consider this illustrative example—not a local insurance estimate:
| Insurance expense | Initial budget | Property quote |
|---|---|---|
| Annual premium | $1,800 | $3,600 |
| Monthly equivalent | $150 | $300 |
That difference adds $150 per month, or $1,800 per year, to your expected expenses.
The question becomes: does the home still fit comfortably once you account for the actual cost of ownership?
Ask your lender to update the payment estimate using the property’s insurance quote. Doing this early gives you time to evaluate your options.
A Lower Premium Can Come With a Bigger Financial Exposure
Two quotes with different prices may also provide different protection. Before choosing a policy, ask a licensed insurance professional to explain:
Replacement cost versus actual cash value: Actual cash value accounts for depreciation, potentially leaving you with more out-of-pocket expense.
Roof coverage: Confirm how a covered roof loss would be settled and whether special limitations apply.
Deductibles: Understand both the standard deductible and any separate wind or hail deductible.
Coverage limits: Ask whether the dwelling limit adequately reflects rebuilding needs.
Optional protection: Discuss water backup coverage and other endorsements relevant to the property.
North Carolina’s insurance department explains that replacement cost and actual cash value coverage can produce different claim payments. It also identifies water backup as a coverage gap that may require an endorsement.
Ask what you would need to pay after a covered loss—not just what you will pay each month.
For example, if a policy’s wind or hail deductible is 2% of a $600,000 dwelling coverage limit, that deductible would be $12,000. Percentage deductibles can create a substantial expense, so confirm the calculation in the specific policy.
Lake Norman Buyers: Separate the View From the Coverage
A beautiful lake view does not tell you what an insurance policy covers.
Standard homeowners insurance generally excludes flood damage. Buyers who want flood protection typically need a separate policy. This deserves consideration for inland properties as well as homes near the water.
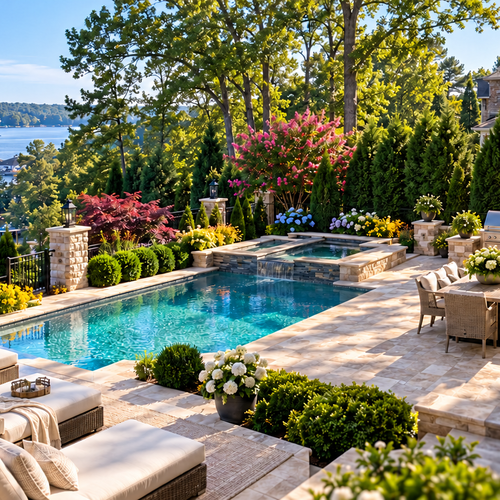
For a Lake Norman property, ask your insurance professional about the house and its additional features: a dock, detached garage, pool, outdoor kitchen, or other structures. Confirm how each would be covered and whether additional protection is appropriate.
Luxury buyers should also discuss coverage limits for valuables and specialty belongings. Standard policies may limit protection for items such as jewelry and certain collections.
Make Insurance Part of Your Due Diligence
A practical approach is to investigate insurance as soon as a property becomes a serious contender, then confirm the details promptly once under contract.
Request a property-specific quote. Provide accurate information about the home, intended occupancy, and relevant features.
Compare equivalent coverage. Look beyond the premium to limits, exclusions, deductibles, and endorsements.
Ask about eligibility and conditions. Find out whether coverage depends on repairs, inspections, or additional documentation.
Share the quote with your lender. Confirm its effect on your payment estimate and qualification.
Coordinate timing. Work with your insurance professional, lender, and real estate broker to address questions before applicable deadlines.
An early quote helps turn an uncertain expense into a decision you can evaluate.
What Sellers Can Do Before Listing
Sellers can help buyers investigate the property by organizing accurate records, including roof replacement dates, repair documentation, and information about major improvements.
Avoid promising that a buyer will qualify for the same policy or premium you currently have. Instead, make useful property information available so the buyer’s insurance professional can evaluate it.
A well-prepared seller helps reduce unanswered questions during the transaction.
Frequently Asked Questions
Should I get an insurance quote before making an offer?
When practical, an early estimate can help you evaluate affordability. Once under contract, promptly confirm coverage availability and any insurer requirements.
Is homeowners insurance legally required in North Carolina?
North Carolina law does not generally require homeowners insurance, but a mortgage lender typically requires it.
Does homeowners insurance cover flooding?
Standard homeowners policies generally exclude flood damage. Discuss separate flood coverage with a licensed insurance professional.
Is the cheapest quote the best choice?
Compare the protection as well as the price. A lower premium may involve a higher deductible or different coverage terms.
Buy With a Budget That Reflects the Whole Home
A confident purchase starts with understanding the costs before they become surprises.
Whether you are purchasing your first home, relocating to North Carolina, or considering a luxury property around Lake Norman, I help you identify important questions and coordinate with the professionals who can answer them.
Let’s find a home that fits your lifestyle and your ownership budget. Visit LivingInStyleRealty.net or contact Javier Sims Davila at 704-870-7057 to begin planning your next move.
Policy terms and eligibility vary. Consult a licensed insurance professional for property-specific coverage advice.
About the Author
Javier Sims Davila is the Founder and Broker-in-Charge of Living In Style Realty, partnered with Southern Homes of the Carolinas. With more than 30 years of client-forward service, he serves buyers, sellers, investors, and relocation clients throughout Lake Norman and surrounding North Carolina communities. Javier offers service in English and Spanish, combining local knowledge, skilled negotiation, and attentive guidance.
Check out this article next